
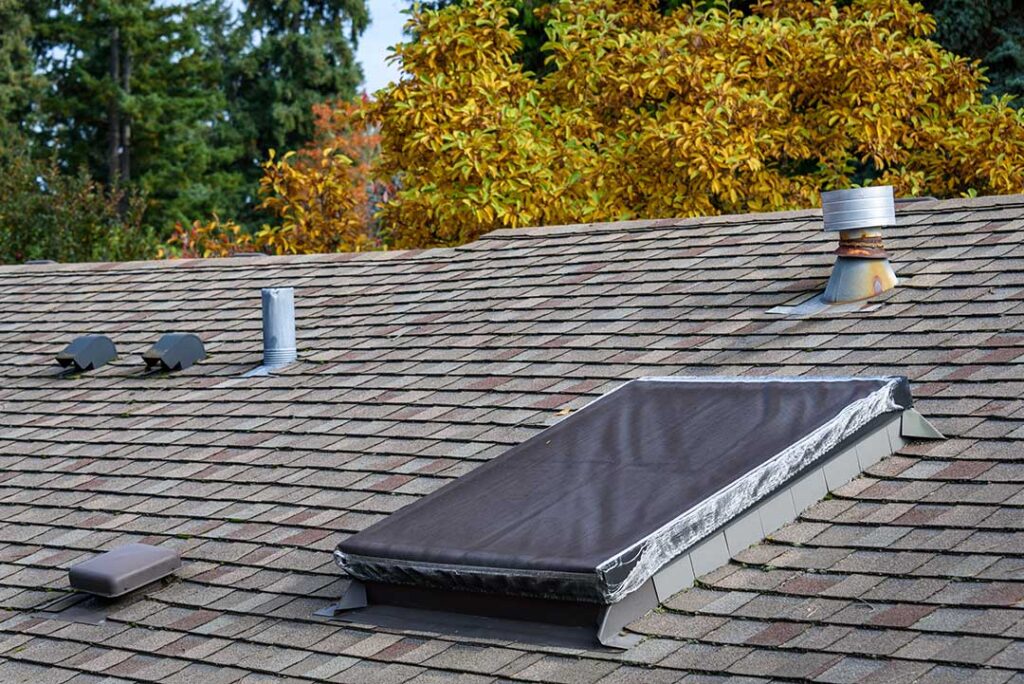
Does homeowner’s insurance cover roof damage?
Usually, homeowner’s insurance covers sudden roof damage caused by a covered event, such as wind, hail, fire, falling trees, or the weight of certain weather-related debris. It generally does not cover damage caused by age, ordinary wear, poor maintenance, or a roof that has been leaking gradually.
The exact answer depends on the policy language, the cause of loss, the roof’s condition, and the type of coverage purchased. A policy may cover the resulting interior damage even when it does not pay to replace an old roof, but that distinction is not automatic. The insurer will usually investigate how the damage occurred.
For households in Ithaca, winter conditions can complicate roof claims. Snow, ice, freeze-thaw cycles, wind, and fallen branches can expose weak areas in shingles, flashing, vents, and roof edges. A claim is more likely to be questioned if an inspection shows that the storm revealed a pre-existing maintenance problem rather than creating the primary damage.
What roof problems are usually excluded?
Insurance is designed mainly for unexpected damage, not routine upkeep. Common exclusions or limitations include:
- Shingles that have deteriorated because of age
- Damage from long-term leaks
- Rot caused by neglected moisture intrusion
- Moss or organic growth by itself
- Poor installation or defective construction
- Inadequate ventilation or condensation problems
- Damage that existed before the policy began
- Cosmetic damage that does not affect the roof’s function
A roof may look acceptable from the ground while still having worn seals, brittle shingles, damaged underlayment, or deteriorated flashing. Regular maintenance does not guarantee coverage, but a documented history of reasonable care can help establish the roof’s condition before a loss.
Insurance companies may also consider the roof’s age when deciding whether to write or renew a policy. Some policies limit payment to the roof’s actual cash value rather than its full replacement cost, particularly when the roof is older.
What is the difference between replacement cost and actual cash value?
Replacement cost coverage is intended to pay the cost of replacing covered damage with materials of similar kind and quality, subject to the policy terms and deductible. Actual cash value subtracts depreciation for age and condition.
For example, if a storm damages a section of an older roof, an actual-cash-value settlement may reflect the remaining useful life of the shingles rather than the full price of new roofing materials. A replacement-cost policy may initially issue payment based on the depreciated amount and release additional funds after completed repairs, if the policy allows that process.
The declarations page and policy endorsements should identify how the dwelling and roof are covered. Do not assume that the policy automatically provides full replacement cost simply because the home itself is insured.
How does the deductible affect a roof claim?
The deductible is the amount the homeowner pays before insurance contributes to a covered loss. A standard deductible may be a fixed dollar amount, while a wind-related deductible may be calculated as a percentage of the dwelling coverage limit.
A percentage deductible can be much larger than many homeowners expect. If a home has a $300,000 dwelling limit and a 2 percent wind deductible, the deductible would be $6,000. That amount applies before the insurer pays for covered damage, subject to the policy’s terms.
Before filing a claim, compare the likely repair cost with the applicable deductible. A small repair may not exceed the deductible, but delaying action can allow water damage to spread. The decision should account for both the immediate loss and the risk of additional damage.
What should be done after a storm damages the roof?
Safety and documentation should come first. Do not climb onto a wet, icy, steep, or visibly unstable roof. Instead:
1. Look for visible signs of damage from the ground or from safe interior areas.
2. Photograph fallen branches, missing shingles, damaged flashing, ceiling stains, and water entry.
3. Write down when the damage was discovered and what weather occurred beforehand.
4. Move furniture and belongings away from active leaks if it can be done safely.
5. Use temporary measures to limit additional damage, such as containers beneath leaks or a properly placed tarp when conditions allow.
6. Notify the insurer promptly and ask what documentation is required.
7. Keep receipts for emergency materials, temporary protection, cleanup, and other reasonable expenses.
Temporary protection is generally different from permanent repair. Avoid removing undamaged roofing materials or authorizing extensive work before the insurer has had a reasonable opportunity to inspect, unless immediate action is necessary to protect the home.
Does insurance pay for interior water damage from a roof leak?
It may, but the cause of the leak matters. If wind creates an opening and rain enters through that opening, the resulting damage may be covered under the policy. If the leak developed slowly because flashing failed over many years, the claim may be limited or denied.
Interior damage can include wet insulation, damaged ceilings, wall finishes, flooring, and personal belongings. Mold, rot, and repeated seepage may have separate exclusions or limitations. Prompt reporting and thorough photographs can help show the sequence of events.
Additional living expense coverage may apply if a covered loss makes the home uninhabitable. This coverage generally concerns the increased cost of temporary housing and necessary living expenses, not every expense associated with being displaced.
Are floods, ice dams, and sewer backups covered?
Standard homeowner’s insurance usually does not cover flood damage. Flood coverage is generally purchased separately, and the definition of flooding can include water that enters from outside and rises over normally dry land.
Ice dam coverage varies by policy. Some policies cover resulting interior water damage when an ice dam causes water to enter, while others exclude or limit certain forms of ice-related loss. Preventive maintenance and proper attic ventilation may also affect how a claim is evaluated.
Sewer backups and sump pump failures are commonly excluded unless a specific endorsement has been added. This is especially relevant for homes with basements, lower-level living areas, or drainage systems affected by heavy precipitation and rapid snowmelt.
What roof records should homeowners keep?
Useful records include:
- The approximate installation date and roofing materials
- Invoices, permits, warranties, and inspection reports
- Photographs of the roof taken during different seasons
- Receipts for repairs, gutter work, flashing repairs, and storm cleanup
- Notes about previous leaks and how they were corrected
- A current home inventory with photographs of valuable belongings
- The declarations page and endorsements for the current policy
Review the dwelling coverage limit periodically. Rebuilding costs can change because of labor, materials, code requirements, and improvements made to the home. The market value of the property is not the same as the cost to rebuild it.
What if the insurer denies the claim or the payment seems too low?
Ask for the decision in writing and request the specific policy language supporting the denial or limitation. Compare the insurer’s explanation with the inspection findings, photographs, repair records, and any contractor estimates.
New York homeowner policies generally include an appraisal process for disputes about the amount of a covered loss, although appraisal does not usually decide whether the policy covers the event in the first place. If communication breaks down, homeowners can seek guidance from the New York State Department of Financial Services or obtain legal advice about the particular dispute.
A roof claim is easier to evaluate when the damage, timing, maintenance history, deductible, and coverage type are clearly documented. Understanding those details before severe weather arrives can prevent confusion when the home needs immediate protection.
