
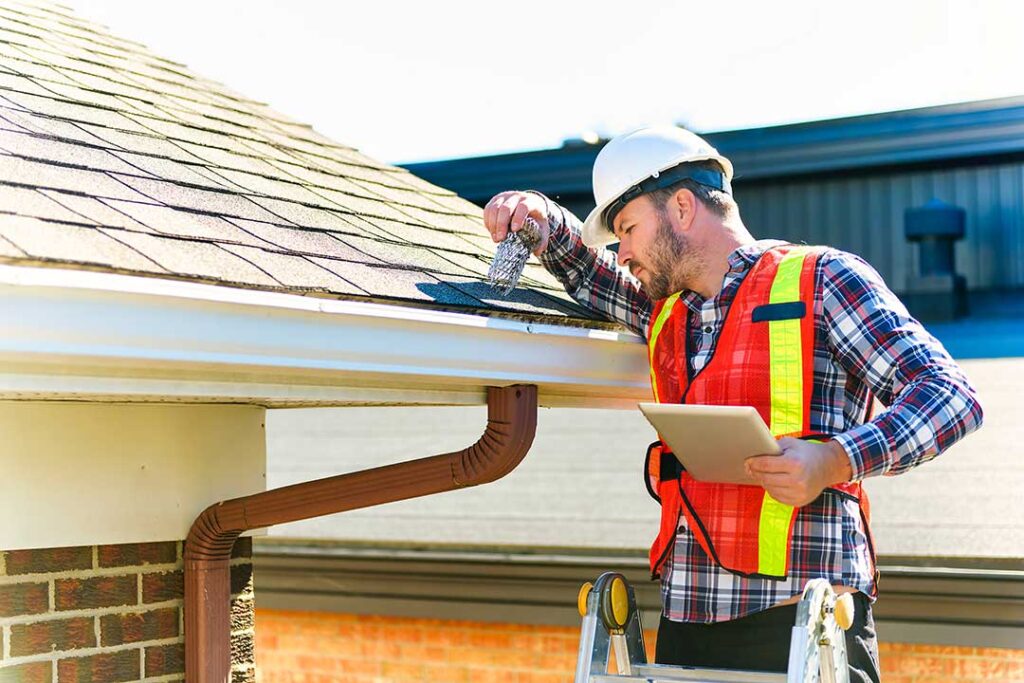
Roof damage is easier to evaluate when the facts are recorded before debris is moved or repairs begin. For residents of Ithaca, NY, that usually means documenting the roof, interior leaks, affected belongings, weather conditions, and emergency work in a clear timeline.
A well-organized record does not guarantee coverage. Insurance decisions depend on the policy, the cause of loss, the roof’s condition, deductibles, exclusions, and whether the damage was sudden or the result of long-term deterioration. Good documentation simply gives the insurer a more reliable picture of what happened.
What should be documented first after roof damage?
Start with safety, then create a visual record before cleaning up. Do not climb onto a wet, icy, steep, or visibly unstable roof. Ground-level photographs and videos are safer than trying to inspect every roof surface personally.
Record:
- The date and approximate time the damage was discovered
- The date and time of the suspected storm or weather event
- Wind, hail, heavy rain, ice, snow, or falling-tree conditions that were observed
- Wide views of the entire house and roof
- Close-up views of missing, lifted, cracked, bruised, or displaced roofing materials
- Damaged flashing, vents, gutters, downspouts, siding, windows, chimneys, and exterior trim
- Water stains, dripping areas, bubbling paint, damaged ceilings, and wet insulation indoors
- Fallen branches, tree limbs, or other objects that struck the structure
- Damaged furniture, clothing, electronics, flooring, and other personal property
Take photographs from several angles. A close-up may show a broken shingle, but a wider image helps establish where that damage is located on the roof.
How can photographs and video be made more useful?
Photographs should show both the damage and its setting. Include a reference object, such as a ruler or tape measure, when it can be done safely. Avoid altering the scene before photographing it unless immediate action is needed to prevent additional damage.
Helpful practices include:
- Photographing each roof slope from the ground when possible
- Taking the same area from far away, at medium distance, and close up
- Using a flashlight to document attic moisture or darkened wood
- Recording a slow video that shows the outside of the property and interior rooms
- Keeping the original files rather than relying only on edited or compressed versions
- Saving copies in more than one location
- Naming files with the date, room, and subject, such as “2026-10-16-kitchen-ceiling-leak”
Do not use filters, drawings, or heavy editing that could make the condition unclear. If a photograph is taken after an emergency repair, label it as such.
What information belongs in a written damage log?
A written log fills in details that photographs cannot show. Use one document or spreadsheet and update it as new information becomes available.
For each event or observation, record:
- Date and time
- What happened
- Where it happened
- What was visible
- What action was taken
- Who was present
- Any cost incurred
- The related receipt, photograph, video, or report
For example, a useful entry might state that water began appearing on a second-floor ceiling during a period of heavy rain, a bucket was placed below the leak, and an emergency tarp was installed the following morning. Avoid guessing about the cause unless the cause has been verified. “Water entered near the upper hallway ceiling” is more precise than “the whole roof failed.”
Keep a record of telephone calls, emails, claim numbers, inspection dates, and the names of people involved. After an important conversation, write down what was discussed while it is still fresh.
Should the roof be repaired before an insurance inspection?
Emergency measures may be necessary to prevent further damage, but permanent repairs should generally wait until the insurer has had a reasonable opportunity to inspect the loss. The policy may also require prompt notice of damage.
Temporary steps can include:
- Placing containers under active leaks
- Moving furniture and personal property away from water
- Covering openings with a tarp when it can be done without creating a safety hazard
- Removing limited amounts of standing water
- Arranging for damaged utilities to be made safe
- Boarding broken openings when needed
Save receipts for tarps, emergency labor, drying equipment, temporary lodging, and other reasonable expenses. Photograph the condition before and after temporary work. Keep removed materials, damaged belongings, and debris when doing so is safe and practical. If something must be discarded because it presents a health or safety danger, photograph it thoroughly first and record why it was removed.
What roof and property records should be gathered?
Insurance companies may ask for evidence of the roof’s age, prior condition, maintenance, and repair history. Useful records include:
- The insurance declarations page and applicable endorsements
- The policy number and deductible information
- Previous inspection reports
- Roofing invoices, contracts, warranties, and receipts
- Permit or completion records, when available
- Photographs of the roof taken before the loss
- Records of earlier leaks or repairs
- Receipts for emergency work
- A household inventory with approximate purchase dates and values
- Bank or credit-card records for expensive items if receipts are unavailable
This information can help distinguish new storm damage from older wear, deferred maintenance, or a prior unrepaired condition. It is better to state that a roof was installed “around 2015, according to available records” than to present an uncertain date as fact.
How do Ithaca weather conditions affect documentation?
Homes in Ithaca can experience repeated freeze-and-thaw cycles, heavy snow, ice buildup, wind-driven rain, and falling branches. These conditions can produce overlapping symptoms. For example, a ceiling stain may become visible during a rainstorm even though water entered through damage caused earlier by ice or wind.
Document the weather event as specifically as possible:
- Note whether precipitation was rain, wet snow, sleet, or hail
- Record whether snow or ice was present on the roof
- Photograph fallen limbs, ice dams, or displaced materials
- Note whether water appeared during the storm or afterward
- Record damage to nearby structures, trees, gutters, and exterior surfaces
Do not assume that the most recent storm caused every visible problem. An adjuster may compare current photographs with earlier records and may look for evidence of long-term leakage or deterioration.
Does homeowners insurance cover every roof leak?
No. Coverage depends on the policy and the cause of damage. Sudden damage from certain covered events may be treated differently from deterioration, poor maintenance, defective installation, insects, rot, or repeated seepage.
Standard homeowners policies commonly exclude flood damage, and water entering through an opening may be evaluated differently from water rising from outside the structure. A roof that is old or worn may also have different settlement terms than a newer roof. The declarations page, policy wording, endorsements, and exclusions matter more than general assumptions about what “homeowners insurance” covers.
Documentation should describe facts rather than argue that coverage applies. The insurer determines coverage under the policy, while the homeowner’s records establish what occurred and what was damaged.
What mistakes can weaken a roof damage record?
Several common mistakes make claims harder to evaluate:
- Climbing onto a dangerous roof and getting injured
- Cleaning up before taking photographs
- Throwing away damaged materials without documenting them
- Making permanent repairs before inspection
- Reporting guesses as confirmed facts
- Failing to document interior and personal-property damage
- Losing receipts for emergency work
- Relying only on verbal conversations
- Waiting too long to report the loss
- Assuming a contractor’s opinion is the same as an insurance coverage decision
If structural instability, electrical hazards, exposed wiring, severe leaking, or fallen trees create danger, stay clear of the affected area and use qualified assistance where necessary. Safety takes priority over obtaining a perfect photograph.
When should the documentation be submitted?
Notify the insurer as soon as reasonably possible under the policy’s requirements. Ask what forms, photographs, receipts, estimates, inventories, and proof-of-loss documents are needed. Submit organized copies and keep the originals.
Arrange the file in sections:
1. Claim and policy information
2. Timeline of the event
3. Exterior photographs
4. Interior photographs
5. Damaged belongings
6. Temporary repairs and expenses
7. Roof history and prior records
8. Communication log
A clear file helps prevent missing information and makes it easier to answer follow-up questions. It also preserves a record if the claim changes as hidden moisture, insulation damage, or additional interior problems become visible.
